
Capitalize on today's evolving market dynamics.
With changes to taxes and interest rates, it's a good time to meet with a wealth advisor.
Strong corporate earnings, consumer spending and business investment have fueled stock gains, although rising bond yields leave less room for disappointment and increase correction risk.
Inflation, Federal Reserve policy, energy disruption or credit stress could weaken demand, profits or financing and trigger a market correction.
Wider participation across S&P 500 sectors, smaller companies and international stocks reduces reliance on a narrow group of technology leaders.
The U.S.-based S&P 500 reached an all-time high in mid-August after absorbing sharp swings tied to the Iran conflict and higher energy prices. As of August 13, the index stood nearly 22% above its March 30 low, although prices through September 10 have eased more than 2% from the high.1 The rebound shows investors are weighing geopolitical uncertainty, inflation and rising bond yields against economic growth and corporate profits.
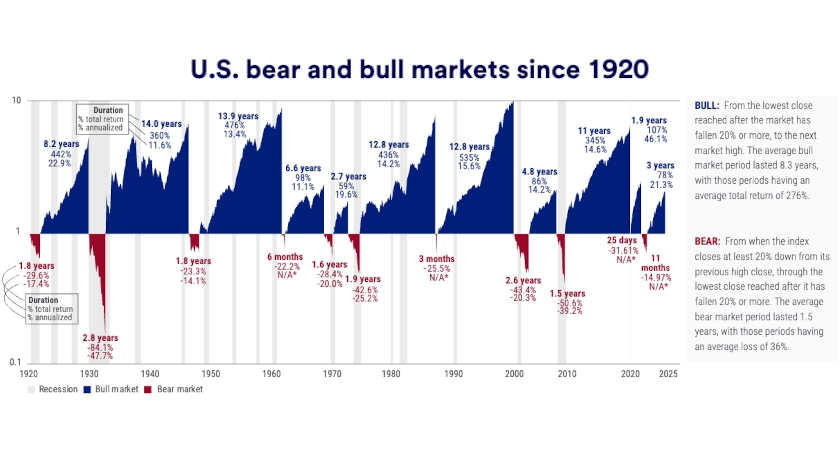
A market correction generally describes a decline of at least 10% from a recent high, while a drop of 20% or more defines a bear market. The S&P 500 fell about 8% from February 27 through March 30 during the initial phase of the Iran conflict, then recovered before reaching correction territory.1 That episode shows how quickly markets can adjust to new information without developing into a stock market crash.
The market’s next move will depend less on one headline than on its economic effects. Corporate profit trends, household demand, inflation, interest rate policy and energy costs will shape whether today’s market levels remain justified. These indicators offer a clearer guide than an attempt to predict the exact start of the next pullback.
Corporate earnings provide the strongest foundation for share prices near record highs. With 99% of S&P 500 companies reporting second-quarter results, aggregate revenue rose 15% and earnings increased more than 53% from a year earlier.1 Analysts also expect earnings to rise 32% for all of 2026 and another 15% in 2027, extending the solid fundamentals behind the market’s climb.1
Business investment has strengthened the profit cycle, particularly through spending on artificial intelligence (AI) infrastructure. Large technology companies with extensive cloud and data center networks, sometimes called hyperscalers, are buying advanced chips, servers, networking equipment and power capacity. These outlays create revenue for technology suppliers, utilities, industrial companies and other businesses that build and operate AI systems.
Investors are assessing whether these projects will produce attractive financial returns. A sustained investment cycle could improve productivity and create new revenue opportunities across the economy. Alternatively, slower outlays or weaker returns could weigh on AI-linked market leaders and increase market correction risk.
The 2026 rally has expanded beyond the largest information technology and communication services companies. Through September 10, 10 of 11 S&P 500 sectors produced positive year-to-date returns, including energy, technology, materials and industrial sectors. Mid-cap and small-cap stocks also advanced, showing that gains have reached companies well beyond the largest index members.1
International stocks have participated as well. Developed-market stocks represented by the MSCI EAFE Index and emerging-market stocks represented by the MSCI Emerging Markets Index posted positive year-to-date returns through September 10.1 Broader gains across regions, sectors and company sizes reduce the market’s dependence on a narrow source of return.
“Markets tend to be more resilient when leadership broadens because performance does not depend on one sector or region going right,” says Rob Haworth, senior investment strategy director for U.S. Bank Asset Management Group. “Wider participation has helped offset volatility tied to geopolitics and company-specific concerns.” A broad rally can signal that investors are responding to fundamental business strength, rather than simply following recent price momentum.“Markets tend to be more resilient when leadership broadens because performance does not depend on one sector or region going right,” says Rob Haworth, senior investment strategy director for U.S. Bank Asset Management Group. “Wider participation has helped offset volatility tied to geopolitics and company-specific concerns.” A broad rally can signal that investors are responding to fundamental strength, not just a narrow momentum trade.
Household purchases continue to generate company revenue, although financial conditions vary across consumers. Higher-income households sustain much of the activity in travel, dining and other discretionary purchases, while middle-income consumers remain more selective and lower-income households face pressure from food, fuel and borrowing costs. This uneven foundation can sustain near-term profits, but it also makes demand more vulnerable to slower hiring, weaker asset prices or another increase in essential expenses.
The labor market continues to expand at a restrained pace after hiring recovered from a weak start to the summer. Employers added 162,000 jobs in August, and the unemployment rate held at 4.1%, according to the Bureau of Labor Statistics (BLS). Modest hiring and low layoffs preserve household income and spending, but slower wage gains reduce the economy’s cushion because weaker income growth can restrain demand even before unemployment rises sharply.
“Estimated earnings growth for 2026 is 33%, followed by 15% in 2027, according to Bloomberg, FactSet and S&P Capital IQ,” says Terry Sandven, chief equity strategist for U.S. Bank Asset Management Group. “Those forecasts reflect expectations for resilient business investment and consumer spending.” Investors will compare those forecasts with incoming results because weaker demand or narrowing profit margins could challenge the market’s current valuation.
Inflation can pressure stocks through several channels. Average hourly earnings rose 3.1% from a year earlier in August, while the Consumer Price Index increased 3.4% in the 12 months through August, leaving wages with less purchasing power support than earlier in the expansion.2 Persistent inflation can also raise company costs, limit profit margins and keep borrowing costs elevated for consumers and businesses.
Federal Reserve policy and bond yields influence stock valuations, which reflect the prices investors pay today for expected future profits. The Fed held its federal funds target range at 3.50% to 3.75% on July 29, but since that meeting, rising oil prices have led investors to expect rate hikes later this year, translating to rising bond yields. Higher interest rates and longer-term bond yields make bonds more competitive with stocks, increase borrowing costs and lower the value investors place on future earnings, although strong corporate profits can outweigh some of that strain.
Energy prices connect geopolitical conflict with inflation and stock market risk. Current conditions fit a disrupted-but-absorbing scenario: shipping remains constrained, but inventory draws, reserve releases, added production, alternate routes and shifts in demand continue to cushion lost supply. A more severe supply shock would require persistent restrictions and weaker offsets at the same time, posing a greater threat to consumer spending, economic activity and corporate profits than a temporary price increase.
Market corrections often begin when investors lower their expectations for economic growth, earnings or interest rates. A sustained rise in energy and transportation costs could lift policy rate and inflation expectations, pushing bond yields higher at the same time. Credit stress, such as a wave of missed debt payments, the failure of a major borrower or trouble at a financial institution, could also turn a contained problem into a broader market decline.
“Corrections usually occur when risks move from potential to economic reality. Markets are watching whether today’s uncertainties begin to affect growth, earnings and financial conditions, while corporate earnings strength has outweighed those risks so far.”
Bill Merz, head of capital markets research for U.S. Bank Asset Management Group
Credit stress can spread when lenders charge more interest, limit new loans or refuse to refinance existing debt. Tighter financing conditions can force households and businesses to cut spending, erode company revenue and profits, and lead investors to demand lower stock prices as compensation for greater risk. The 2008 financial crisis offers the clearest modern example of credit problems spreading through financing, economic activity and markets, although a smaller default does not automatically produce the same outcome.
“Corrections usually occur when risks move from potential to economic reality,” says Bill Merz, head of capital markets research for U.S. Bank Asset Management Group. “Markets are watching whether today’s uncertainties begin to affect growth, earnings and financial conditions, while corporate earnings strength has outweighed those risks so far.” Investors should watch for signs that higher costs are eroding demand, profits or access to financing.
Periods of volatility often test discipline more than strategy. Investors can start by confirming that portfolios still align with long-term goals and with their comfort level for risk, especially after strong market gains. Market swings do not change time horizons, but they can highlight whether allocations remain appropriate.
For those holding excess cash, a phased approach, gradually putting money to work, can reduce the pressure of trying to pick the perfect day to invest. Reviewing diversification across asset types and regions can also reveal gaps or missed opportunities. These steps emphasize preparation and risk control rather than short-term prediction.
“Volatility creates uncertainty, but it does not eliminate the value of a long-term plan,” says Tom Hainlin, national investment strategist with U.S. Bank Asset Management Group. “Staying invested and diversified and making measured adjustments helps investors remain focused on outcomes that matter over time.” A thoughtful discussion with a wealth planning professional can help separate temporary market noise from developments that may change the long-term outlook and can ensure your investment strategy still aligns with your time horizon, risk appetite and financial goals.
A market correction usually refers to a decline of about 10% to less than 20% from a recent high, while larger declines are often described as bear markets. Corrections can occur even when the economy is growing and often reflect shifting expectations rather than lasting damage. They are a normal part of market cycles.
Historically, the S&P 500 has experienced average intra-year declines of roughly 14% since 1990, even as long-term returns have remained positive.1 That history shows why pullbacks can occur during otherwise strong years. Understanding this pattern can help investors keep perspective when prices move quickly.
Market corrections can last days, weeks or months, and timelines vary because different catalysts unwind at different speeds. The average correction (10% to 20% decline) lasts 17 days, but any single episode can run shorter or longer depending on whether the decline reflects temporary shifts in expectations or deeper economic stress.1 Recoveries also vary because markets often price in new information before it shows up in slower-moving economic data.
Corrections occur often enough that long-term investors generally treat them as part of the market’s regular rhythm rather than as rare events. The S&P 500 has spent 29% of its history since 1927 trading 10% or more below a recent high, which shows that double-digit pullbacks have been common over time.1 That history does not predict the next move, but it helps investors frame volatility as a recurring feature of markets.
Key indicators of a market correction include rising market volatility, sustained increases in energy or interest rates, and growing uncertainty around economic growth or corporate earnings. Corrections become more likely when higher costs or tighter borrowing conditions start to affect consumer spending or business investment. Short-term headlines alone rarely drive sustained declines; lasting changes in economic conditions usually carry more weight.
Many investors start by separating time horizons. Short-term moves can look dramatic, while long-term plans often assume periodic pullbacks along the way. Diversification can help because different investments may respond differently to growth, inflation and interest-rate shifts, which reduces reliance on a single outcome.
Yes, stock market corrections can occur even when the economy is strong. Corrections often follow changes in investor expectations, starting valuations or external shocks such as geopolitical conflict or government policies. Strong economic indicators can support the broader outlook, but they do not prevent periods of market volatility.
Changing interest rates can influence market corrections by changing borrowing costs and how investors value future profits. When interest rates rise, borrowing often becomes more expensive, which can slow economic activity and pressure stock prices as expectations adjust. When interest rates fall, financing typically becomes cheaper, which can support spending and investment and may soften or delay a correction.
Typical warning signs leading to a pullback in the stock market include stretched stock prices, rising interest rates and increasing economic uncertainty. Additional indicators can include weakening corporate earnings, unusually one-sided positioning or heightened geopolitical instability. Investors often watch for when these risks start to show up in real activity, such as slower spending or tighter credit, rather than relying on headlines alone.
The S&P 500 Index consists of 500 widely traded stocks that are considered to represent the performance of the U.S. stock market in general. Equity securities are subject to stock market fluctuations that occur in response to economic and business developments. Diversification and asset allocation do not guarantee returns or protect against losses.

Discover how the stock market is impacted by the policies enacted during President Trump’s second term in the White House.

We can partner with you to design an investment strategy that aligns with your goals and is able to weather all types of market cycles.


 Equal Housing Lender. Deposit products are offered by U.S. Bank National Association. Member FDIC. Mortgage, Home Equity and Credit products are offered by U.S. Bank National Association. Loan approval is subject to credit approval and program guidelines. Not all loan programs are available in all states for all loan amounts. Interest rates and program terms are subject to change without notice.